Author name: Goo Finance

SIP vs Mutual Funds
Investment

SIP vs Mutual Funds: What is the Difference? 2026

SIP vs Mutual Funds: A cousin of mine had once asked me, in all seriousness, if he should ‘do a SIP or just buy a mutual fund’. I sympathized with his dilemma. We are all so used to seeing these two words bandied about in every bank’s advertisement and financial influencer’s video, as if they were diametrically opposed products They are not. A cursory two minute elucidation on the subject will free you from being tied up between the two. What is a mutual fund? Imagine thousands of people pooling in money into one pot and a fund manager investing the corpus in a variety of shares, bonds, gold, etc. The investors would receive a certain number of units in return and the value of these units would be known as the Net Asset Value (NAV). The NAV tends to increase as the value of the stocks, bonds, etc in the fund increase. Similarly, it decreases when the latter decreases. Some common types of funds are: What is a SIP? A SIP or a Systematic Investment Plan is a plan. You cannot really own a SIP. A SIP is a standing instruction to your bank to electronically transfer a certain amount of money to a fund of your choice every month. A lot of schemes offer SIPs starting with as low as ₹500 (roughly the price of two meals at McDonalds). A SIP is ideal for someone who is averse to the idea of going to an ATM or the bank. The difference explained In short, a mutual fund is a product; a SIP is a plan. To put it in perspective, think of it as purchasing a phone. You can either pay the entire amount at once or go for an EMI. The product remains the same, the difference is in the method employed at the time of purchase. In order to compare SIP vs mutual funds, you would actually have to perform a SIP vs lump sum analysis. What is the difference between a SIP and a mutual fund? A comprehensive list An example to illustrate the above bullet point Let us assume that you have invested ₹ 5,000 every month in an equity fund. Every month, this money is being used to purchase units of the fund. When the market is performing well, the fund will give you lesser units and when it is performing poorly, the number of units would be higher. Over time, this method of averaging out the price is actually beneficial to the investor. This feature, peculiar to SIPs is known as rupee cost averaging. Let us now assume that you continue to invest ₹5,000 for 15 years (9,00,000) in this fund. Let us also assume that the fund provided 12% returns a year (on an annualized basis). The money that you have invested would grow to roughly ₹25,00,000 (this is obviously a hypothetical example). Obviously, the market cannot provide consistent returns for 12 long years, and you will also encounter years of losses. The trend of the market is upwardly sloping though and a SIP ensures that your average returns will exceed the average returns from a lump sum. Why salaried people tend to prefer SIPs Someone who is salaried and whose income comes once a month will appreciate a SIP. Some people prefer SIPs because One popular example of a systematic investment plan is the step up SIP, wherein the amount invested increases by a predetermined amount every year. For instance, you can increase the amount invested by 10% every year (this will also reflect in salary increases if you are employed). These increases negate the inflationary effect of the increased standard of living and allow you to accumulate a significantly larger corpus after 20 years. When lump sum investment makes more sense Sometimes, one has a large amount of money lying idle. For instance, one might receive a bonus or a maturity benefit from a life insurance policy. It may not seem feasible to invest the entire amount at once and wait for two years for the SIP to finish. Here is where a lump sum can be particularly useful. Some reasons why a lump sum might make more sense than a SIP: A good middle ground in this case would be to park this corpus in a liquid or debt fund and transfer it systematically to an equity or hybrid fund (a systematic transfer plan or STP). The risks involved with a SIP It goes without saying that a SIP is not an assured income. A SIP will have all the risk associated with the fund in which it is invested. Some things to remember when considering a SIP are: For equity funds, a five year time horizon is recommended. Similarly, anything shorter than this should be invested in a hybrid or a debt fund. Does a SIP have an impact on the tax? Taxability depends on the fund and the period of holding. However, a SIP is not treated differently from a lump sum. One thing to consider is that every monthly instalment qualifies as a separate purchase and is taxed according to its period of holding The rules governing taxation tend to change often, so it is best to keep an eye on the notifications from the income tax department or consult a chartered accountant. Which option is better? The choice depends on your income pattern and your tolerance for volatility. You can go for a SIP if You can go for a lump sum if Ideally, you should pursue both options. Have a SIP as your primary source of investment and invest lump sums in the fund whenever you have the extra money. Whatever you choose, remember to give the money a role to play. ₹ 2,00,000 earmarked for a house down payment in three years cannot wait for retirement in twenty five years. Common SIP mistakes that you should avoid It is not necessary to review the SIP every morning. Once or twice a
Personal Finance

How to Create a Monthly Budget: A Beginner’s Guide 2026

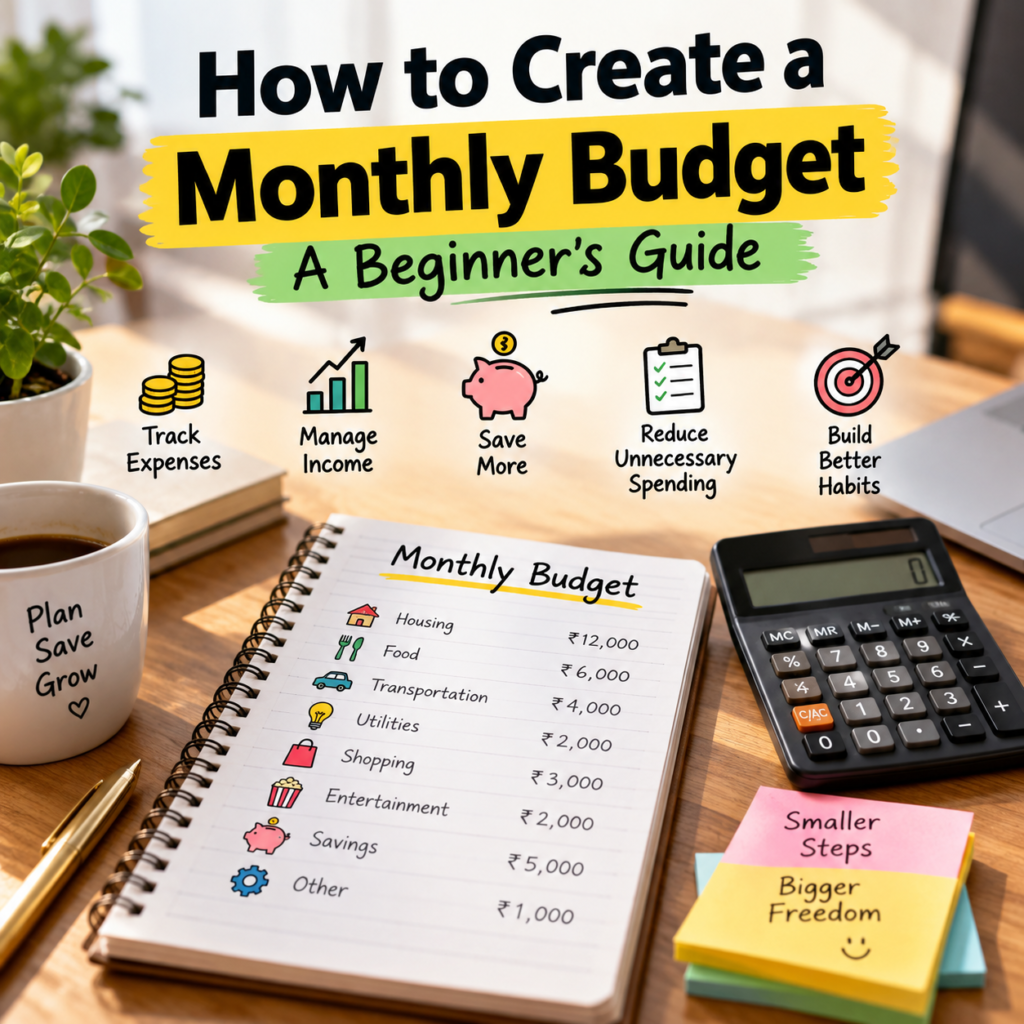
Managing your finances can prove to be more challenging than you anticipated if you do not have a proper understanding of where your hard-earned money goes. Even if you have sufficient income to meet all your expenses, there might still be times when you wonder where all your money went in a blink of an eye. A monthly budget can help you avoid such situations because it serves as an ultimate guide to managing your earnings, expenses, debts, and savings. Moreover, it enables you to stay ahead of your spending. If you have no prior knowledge or experience regarding finances, do not worry. We have a practical solution that all newcomers can follow to create a comprehensive monthly budget with ease and convenience. The Ultimate Guide on How to Make a Monthly Budget What Is a Monthly Budget? A monthly budget simply means a plan or an estimate of how you intend to spend your monthly income. It is a self-explanatory record that highlights your monthly income, expenses, savings, and debts. In other words, a budget helps you understand what you want to achieve financially. It prevents unplanned spending and puts financial discipline in your spending pattern. A sample monthly budget may consist of the following: The objective of a monthly budget is not to restrict your spending. It aims to help you prioritize your expenses according to your financial status and the achievement of your financial goals. Why Creating a Monthly Budget Is Worth Your Time? Without a financial plan, it becomes impossible to keep track of your expenses. It can also be overwhelming when you realize how much you actually spend on a cup of coffee or other mindless activities. In such a case, a well-crafted monthly budget can become your best friend. Here are some reasons why a budget is essential: A monthly budget can also help you stay calm and relaxed about your finances. How to Make a Monthly Budget: Step-by-Step Guide? The simplest method to create a monthly budget is to calculate your monthly income first. If you have a permanent or a stable source of income, then it will be easier for you to prepare an estimated record of your monthly earnings. Remember, you should consider your net income (the amount of money earned after deducting all applicable taxes) while creating a monthly budget. On the other hand, if your income varies from month to month, then you should create a realistic estimate based on your average monthly earnings. For instance, your monthly income consists of: List All Your Fixed Monthly Expenses When we talk about the monthly budget, the first thing that comes to mind is monthly expenses. A monthly budget should ideally highlight your monthly expenses, which include both your fixed and variable expenses. Start with your monthly fixed expenses because they remain the same or vary slightly every month. 2. Some common examples of monthly fixed expenses are: So, after calculating your monthly income, keep a track of all your monthly bills to determine how much percentage of your income is utilized in your monthly expenses. Variable expenses are the ones that vary from time to time or from one month to another. It is always a good idea to keep a track of your variable expenses for at least a month to identify your monthly spending pattern. Some common examples of variable expenses are: In this step, instead of estimating your expenses, it is better to go through your bank account statements or digital wallet transactions and categorize them accordingly. One of the easiest but the most effective ways to create a monthly budget is to sort your expenses into needs vs wants. Your needs mean the things that you cannot live without, whereas your wants are just luxuries that you can live without. For instance, your needs may include: However, your wants may include dining out, latest gadgets and technology, entertainment subscriptions, etc. It is a myth that people with a good income do not save any money. The truth is that people with a high income can also save a significant amount of money if they have a proper budgeting plan. So, it is essential to set realistic monthly savings objectives. To begin with, keep in mind that in a good monthly budget, at least 10% of your income should be allocated towards your savings. In most cases, people save money with specific purposes in mind, such as: So, to begin with, decide on your monthly savings target because it will keep you motivated as you will feel that all your hard work is leading you towards the achievement of your financial goals. An emergency fund plays a critical role in every person’s financial journey. A sudden emergency, unplanned medical expenses, or car repaircan cause a sudden withdrawal of your hard-earned money at the wrong time So, when creating your monthly budget, you should also keep in mind to set aside some money for your emergency fund. To begin with, it is a good idea to save at least Rs. 500 from your monthly income as an emergency fund. However, once your emergency fund grows significantly, you should invest that in a separate bank account so that you cannot just keep touching the money in case of minor issues. In the long run, it is a good idea to save at least 6 months of living expenses as your emergency fund. If you have any loans or credit card dues, then it is essential to highlight your monthly debt repayment plan in your monthly budget. To begin with, create a list of all your debts, along with their interest rates, outstanding amount, and minimum monthly payment. In your monthly budget, always make sure that the money you keep aside for your debt comprises the minimum amount owed. Always pay off that minimum amount on time so that you do not have to pay any late fees. In addition, you can also pay an extra amount to pay

Scroll to Top